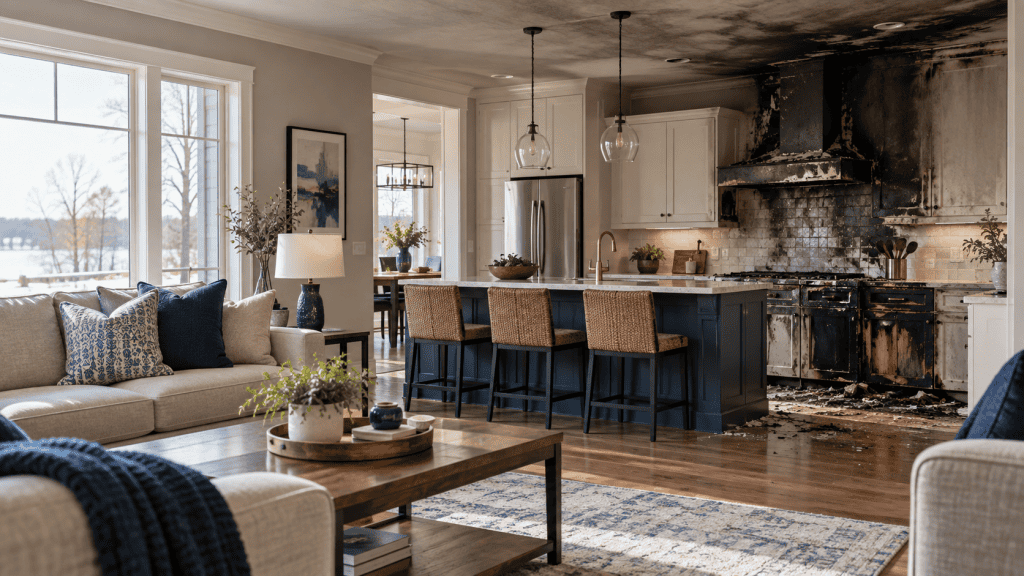
Fire Damage Restoration Cost (Twin Cities)

Fire damage restoration in the Twin Cities costs a median of $22,800 for mitigation in our residential fire records. This phase can include board-up, char removal, smoke and soot cleaning, odor treatment, and drying the water used to fight the fire. Among jobs with documented reconstruction, the median full claim was $241,000.

We pulled these figures from Bedrock Restoration’s residential fire records dating back to 2022. The reported costs include Minnesota sales tax and reflect invoiced work on Twin Cities properties.

A smoke-only cleanup and a whole-home fire are very different projects. To make the numbers useful, we separate mitigation from reconstruction and show the reported ranges for different types of damage.

Fire damage restoration cost at a glance

Type of fire damage Reported mitigation range
Smoke and odor only $950 to $5,500
Contained room fire $10,000 to $30,000
Major or whole-home fire $45,000 to $177,000

Twin Cities Fire Damage Mitigation Costs

Reported cost ranges by damage type, before reconstruction

Fire damage mitigation cost ranges in the Twin Cities Smoke and odor only: $950 to $5,500. Contained room fire: $10,000 to $30,000. Major or whole-home fire: $45,000 to $177,000. Each horizontal bar spans its reported minimum and maximum on the same linear axis from zero to $180,000. These are cost ranges, not job counts or averages. Smoke and odor only Contained room fire Major / whole-home $950–$5,500 $10,000–$30,000 $45,000–$177,000 $0 $30k $60k $90k $120k $150k $180k Mitigation cost (USD)
Source: Bedrock Restoration residential fire records, 2022–September 2026. Includes Minnesota sales tax. Bars show reported cost ranges, not averages or the number of jobs. Reconstruction is excluded.

The middle half of our fire mitigation jobs fell between $6,800 and $47,600. The largest single fire mitigation in our records reached $177,000 before reconstruction began.

Budget for cleanup and repairs separately. The $22,800 median describes mitigation. It does not include the reconstruction needed to replace damaged building materials.

For comparison, our water mitigation median is $3,800. The fire mitigation median is about six times that figure, although the two groups contain different projects and scopes. See our Twin Cities water damage restoration cost breakdown .

What drives fire and smoke damage restoration costs?

A house fire can leave several kinds of damage in the same property. The estimate needs to account for each affected area and the work required to clean, stabilize, and restore it.

Smoke and soot beyond the room that burned

Smoke can reach rooms far from the flames through openings and air movement. Residue may settle on walls, ceilings, furnishings, and other contents. Odor can remain in porous materials even when visible soot is limited.

The smoke damage cleanup cost depends on the affected area, residue, materials, and contents requiring treatment. A small odor cleanup has a different scope from cleaning multiple rooms and their belongings.

Water used to fight the fire

Firefighting water can soak drywall, insulation, and flooring. Extraction, drying, and removal of unsalvageable materials add another scope of work to the fire cleanup.

Burned and heat-damaged materials

Framing, fixtures, and finishes near the fire may require assessment and removal. Materials that cannot be restored also become part of the reconstruction estimate.

Securing the property

Broken windows, damaged doors, and roof openings can leave the home exposed. Board-up and temporary weather protection help secure the property after emergency responders release it.

Contents inventory, cleaning, and pack-out

Furniture, clothing, electronics, and personal belongings may need inventory, packing, transport, cleaning, or loss documentation. The volume and condition of those items can materially affect the scope.

Why an initial fire estimate may miss part of the damage

Visible damage does not always show the full extent of a fire loss. An estimate focused only on the room that burned may overlook smoke residue, hidden heat damage, or water in adjacent spaces.

In one example from our files, a kitchen fire initially appeared to affect a single room. Further inspection identified damage beyond that room, including a scorched dining room outlet two rooms away.

A complete assessment should follow the damage through the property. It should identify affected rooms, contents, and moisture from firefighting, along with any areas requiring further investigation.

When comparing estimates, compare the scope. Check which rooms, surfaces, belongings, and repair phases each estimate includes. A lower initial total may cover less work.

Fire damage repair costs: reconstruction after cleanup

Mitigation cleans, dries, and stabilizes the property. Reconstruction replaces what the fire damaged and what cleanup required crews to remove.

Across 22 Bedrock fire jobs with a documented rebuild, the recorded medians were:

Phase Median cost
Mitigation $39,000
Reconstruction $195,000
Full claim $241,000

Each median is calculated separately, so adding the phase medians does not produce the median full claim. The $39,000 mitigation median applies to this rebuild subset, rather than the full residential fire sample.

In this subset, the reconstruction median is five times the mitigation median. That compares group medians; it is not a multiplier for estimating an individual home’s repairs.

We quote mitigation and reconstruction under separate contracts and perform both under Minnesota contractor license BC787322. Assessing both phases helps connect the cleanup scope with the repairs needed afterward.

Insurance and fire damage restoration costs

In our records, 98% of residential fire losses with a recorded payer ran through homeowners insurance. This describes how those jobs were paid; it does not establish coverage for a particular loss.

Coverage details depend on your policy and circumstances. Ask your insurer about dwelling limits, belongings coverage, deductibles, and additional living expenses while repairs are underway.

Clear documentation helps explain the work needed. That can include photos of affected rooms, a contents inventory, moisture readings, and an estimate that accounts for damage beyond the point of origin.

Steps that can help limit further damage and unexpected costs

  1. Wait for clearance before entering. Follow emergency responders’ instructions before returning to the property or accessing affected rooms.
  2. Arrange property protection promptly. Once access is permitted, discuss board-up, tarping, and mitigation with a qualified restoration team.
  3. Leave affected contents for assessment. Avoid wiping soot or moving damaged items before discussing documentation and handling with your restoration team.
  4. Document the loss when safe. Photograph affected spaces and keep records of estimates, communications, and expenses.
  5. Ask what each estimate includes. Confirm whether contents work, water mitigation, odor treatment, and reconstruction are included or quoted separately.
  6. Discuss changes as hidden damage is found. Ask the team to explain and document additional work before proceeding under the agreed contract process.

Frequently asked questions

How much does fire damage restoration cost?

In our Twin Cities residential fire records, mitigation costs a median of $22,800, including Minnesota sales tax. Reported ranges are $950 to $5,500 for smoke and odor only, $10,000 to $30,000 for contained room fires, and $45,000 to $177,000 for major or whole-home fires. Reconstruction is separate.

How much does smoke damage cleanup cost?

The reported smoke-and-odor-only range in our records is $950 to $5,500. The scope depends on the affected rooms, residue, materials, and belongings requiring treatment.

How much does it cost to repair fire damage to a house, including the rebuild?

Among 22 jobs with documented reconstruction, the median full claim was $241,000. The separately calculated medians were $39,000 for mitigation and $195,000 for reconstruction. An individual property requires its own assessment.

Does fire damage cost more than water damage?

Our residential fire mitigation median is $22,800, compared with $3,800 for water mitigation. The fire median is about six times higher, but these are different groups of projects. Fire losses can combine smoke, soot, heat, and firefighting-water damage.

Is fire damage restoration covered by insurance?

In our records, 98% of residential fire losses with a recorded payer ran through homeowners insurance. Your coverage depends on your policy and the loss. Review limits, deductibles, and living-expense coverage with your insurer.

Dealing with fire or smoke damage? Bedrock handles property protection, cleanup, and reconstruction across the Twin Cities. Call (612) 441-2556 to discuss an assessment, or visit our fire damage restoration services page.

Cost figures are reproduced from the supplied Bedrock Restoration job-record summary covering 2022 through September 2026. Medians reduce the influence of unusually large losses. The fire sample is smaller than the water sample; treat these ranges as directional rather than a quote for your property.

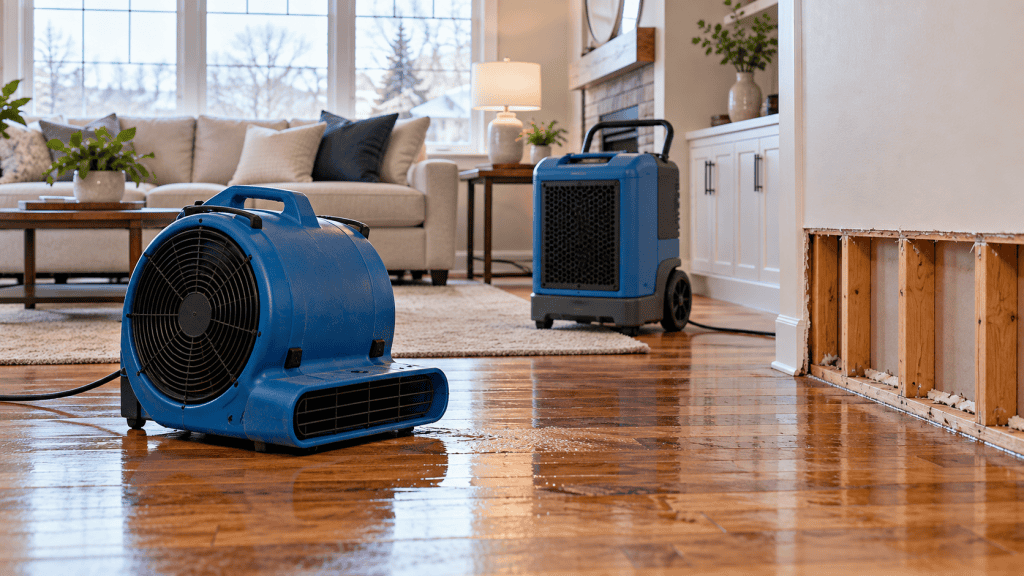
Water Damage Restoration Cost (Twin Cities)

How Much Does Water Damage Restoration Cost? Real Twin Cities Prices for 2026

Water damage restoration in the Twin Cities costs a median of $3,800 for the mitigation phase: extraction, drying, and the demolition needed to dry the structure. In the reported price bands, 56% of mitigation invoices fall between $2,500 and $10,000. For the subset of jobs with documented reconstruction, the median rebuild is $12,150, and the separately calculated median full claim is roughly $17,600.

Those figures come from 1,047 water mitigation invoices in Bedrock Restoration’s own records since 2022, across more than 140 Twin Cities communities. National cost guides average prices from contractor surveys. These numbers reflect invoiced mitigation costs in our Minneapolis and St. Paul area records.

Water damage restoration cost at a glance

Twin Cities Water Damage Mitigation Costs

Share of jobs by mitigation price range · 1,047 invoices

Under $2,500 31%
$2,500–$5,000 32%
$5,000–$10,000 24%
$10,000–$25,000 10%
Over $25,000 4%
Source: Bedrock Restoration water mitigation invoices, 2022–September 2026. Mitigation only; reconstruction excluded. Reported whole-number percentages total 101%; confirm rounding against the underlying counts.
Cost range Share of Bedrock water jobs
Under $2,500 31%
$2,500 to $5,000 32%
$5,000 to $10,000 24%
$10,000 to $25,000 10%
Over $25,000 4%

Mitigation only, before reconstruction. Source: 1,047 Bedrock Restoration water mitigation invoices, 2022 to 2026. Percentages are reproduced as supplied; exact invoice counts were not provided.

Two numbers matter most for planning. 63 percent of water dry-outs come in under $5,000. About 1 in 7 pass $10,000 before a single wall goes back up.

What drives the cost of water damage restoration

Every water job is priced on the same handful of variables. Knowing them helps you read an estimate and spot what’s pushing the number up.

The category of water

The IICRC S500 standard sorts water into three categories, and contamination affects the cleanup scope and cost.

  • Category 1 (clean water): a supply line, faucet, or ice maker line. Materials can often be dried in place.
  • Category 2 (gray water): washing machine or dishwasher discharge, a toilet overflow without feces. Contamination can require additional cleaning and removal of affected materials.
  • Category 3 (black water): sewer backups, toilet overflows with waste, and outside floodwater. Porous materials like carpet, pad, and lower drywall must be removed, and crews work under containment. See sewage cleanup.

How far the water traveled

Water moves sideways under flooring and wicks up drywall. A leak in an upstairs bathroom often reaches the ceiling and walls below. Cost scales with the number of rooms and levels affected.

How long it sat

Time is the biggest cost driver a homeowner controls. Prompt shutoff and extraction can limit how far water spreads. Water found after a weekend away has soaked into subfloor and framing, and after 24 to 48 hours mold becomes a risk that adds mold remediation to the scope.

How much has to come out

Drying in place is the cheapest outcome. Wet drywall, insulation, carpet pad, laminate, and lower cabinets often have to be removed to dry the structure, and materials that need replacement add to the reconstruction scope.

Drying time and equipment

Dehumidifiers and air movers are billed by the day. Most structures dry in three to five days, but dense materials like hardwood and plaster take longer.

Common causes of water damage in our records

Among Bedrock water jobs with a recorded cause, the most common sources were:

Cause Share of recorded causes
Toilet, sink, and shower overflow 24%
Supply lines and plumbing 21%
Roof, storm, and exterior 15%
Sewer and drain backup 11%
Appliances (washer, dishwasher) 11%
Frozen and burst pipe 5%
Water heater and boiler 5%
HVAC and AC condensate 4%

Water jobs with a recorded cause (n = 132). Listed categories total 96%; this is a partial breakdown of the supplied figures.

Supply line failures and sewer backups can create extensive damage. A burst supply line runs at full household pressure until someone shuts the main, and sewer backups are Category 3 by definition. Overflows are the most frequently listed cause in this recorded-cause subset. This table shows frequency, rather than cost by cause.

Reconstruction: the second half of the bill

Mitigation dries the structure. Reconstruction puts back the drywall, flooring, cabinets, paint, and trim that came out.

Across 149 Bedrock water jobs that went on to a documented rebuild:

Phase Median cost
Mitigation (phase 1) $4,450
Reconstruction (phase 2) $12,150
Full claim $17,600

Each median is calculated separately, so the phases do not add up to the full-claim figure.

The reconstruction median is about 2.7 times the mitigation median in this rebuild subset; individual jobs can differ substantially. The largest full water claims in our records passed $60,000. When you are budgeting or sizing an insurance claim, the rebuild is where most of the dollars sit.

Bedrock quotes mitigation and reconstruction as two separate contracts and performs both under Minnesota contractor license BC787322, so you see each number before agreeing to it.

Does insurance cover water damage restoration?

About 3 in 4 residential water losses Bedrock handles run through homeowners insurance. Insured jobs carry a median mitigation cost of $4,700, compared with $2,400 for jobs homeowners pay out of pocket. These groups may differ in severity and scope, so the figures do not show that using insurance itself raises the price.

Whether a specific loss is covered depends on your policy and the cause. Sudden pipe bursts and appliance failures are handled very differently from gradual leaks, flooding, or sewer backups without a backup endorsement. Your insurance agent is the right person for that conversation.

What a restoration company should do is give you an honest ballpark early, so you can compare it with your deductible, and document every step with photos and moisture readings for the claim file.

How to keep water damage costs down

  1. Shut off the water immediately. Every adult in the home should know where the main shutoff is and be able to close it in under a minute.
  2. Call for mitigation the same day. Drying costs climb with every hour water sits in drywall and subfloor.
  3. Photograph everything before cleanup starts. Wide shots of each room plus close-ups of the source help both the estimate and the claim.
  4. Move contents off wet flooring. Furniture legs wick water and stain carpet; aluminum foil or blocks underneath help.
  5. Replace rubber supply lines with braided steel. Toilets, sinks, and washers on rubber lines are among the most frequent failures we see.
  6. Add a sump pump backup and leak sensors. A battery backup protects the basement during storm outages, and inexpensive Wi-Fi sensors alert you at the first drip.

Frequently asked questions

How much does water damage restoration cost? In the Twin Cities, water damage mitigation costs a median of $3,800, based on 1,047 Bedrock Restoration invoices. About 63 percent of jobs cost under $5,000, and roughly 1 in 7 exceed $10,000 before reconstruction.

How much does it cost to repair water damage, including the rebuild? For water jobs that required reconstruction, the median full cost was $17,600 in Bedrock’s records. The median rebuild was $12,150, and the median mitigation on those same jobs was $4,450.

Why does sewage backup cleanup cost more than a clean water leak? Sewage is Category 3 water under the IICRC S500 standard. Porous materials it touches, such as carpet, pad, and lower drywall, must be removed and discarded, and crews work under containment with antimicrobial treatment, which adds labor and materials.

Is water damage restoration cheaper if I pay without insurance? Self-pay jobs at Bedrock have a median mitigation cost of $2,400, compared with $4,700 for insured jobs. These are different groups of jobs, rather than two prices for the same work. The figures do not establish a discount for paying directly.

What is the biggest factor in water damage restoration cost? The amount of material that has to be removed, which depends mostly on how long the water sat and what category it was. Fast shutoff and same-day drying keep more of the structure in place and keep both mitigation and rebuild costs lower.


Need a water damage estimate? Bedrock’s IICRC-certified crews are on call 24/7 across the Twin Cities, with a free written estimate before work starts. Call (612) 834-1501 or learn more about our water damage restoration services.

Cost figures come from Bedrock Restoration job records, 2022 through September 2026. Medians are used because a few very large losses would skew an average.

Does Homeowners Insurance Cover Water Damage in Minnesota? A Twin Cities Homeowner’s Guide

Bedrock Restoration  ·  Homeowner Guide

Does Insurance Cover
Water Damage?

What a Minnesota homeowners policy pays for, what it never covers, and how to keep your claim strong. Written for Twin Cities homeowners.

Coverage comes down to a single question, and it is not the one most people ask. What matters is the cause of the water, not the water itself. Sudden and accidental is covered. Slow, neglected, or from outside is not.

3
Exclusions to know
$5–10K
Typical mold cap
1
Endorsement older homes need
The short answer
Usually, yes

Most homeowners insurance policies in Minnesota cover water damage when it is sudden and accidental, such as a burst pipe or an overflowing water heater. They do not cover gradual leaks, neglected maintenance, or outside flooding, which needs separate flood insurance.

1

Is water damage covered by homeowners insurance?

Usually yes, if the damage was sudden and accidental. The standard HO-3 policy most Twin Cities homeowners carry covers water that escapes suddenly from a plumbing, heating, or appliance system inside the home. If a supply line bursts behind a wall in your Edina house or your dishwasher floods the kitchen overnight, the resulting damage is typically covered, minus your deductible.

The policy pays to dry the structure, tear out ruined drywall and flooring, and rebuild. It does not pay to fix the failed part itself. If a pipe bursts, insurance covers the water damage but not the plumber’s charge to replace that section of pipe.

2

What water damage is not covered?

Three things are almost always excluded: gradual damage, flooding, and neglect. A slow leak under a sink that rots the cabinet over months is treated as a maintenance problem. Water that enters from outside, like an overflowing creek or snowmelt pooling against the foundation, is flood damage and falls outside a standard policy.

  • Gradual leaks you could have caught and fixed
  • Outside flooding from rivers, lakes, or surface water (needs flood insurance)
  • Sewer or drain backups, unless you added that endorsement
  • Damage from lack of maintenance
3

Does homeowners insurance cover a burst pipe?

Yes. A burst pipe is the textbook example of sudden and accidental damage, and it is one of the most common winter claims in the Twin Cities. When temperatures drop below zero in January, water in an uninsulated pipe freezes, expands, and splits the line. The cleanup and repairs are covered.

One catch: if you left the house unheated and the pipe froze because of it, the insurer can deny the claim for neglect. Keeping the heat on, even while traveling, protects your coverage.
4

Does insurance cover basement flooding?

It depends on where the water came from. If a pipe or water heater in the basement fails, that is covered. If groundwater or an overflowing Minnehaha Creek pushes water in through the foundation, that is flood damage and is not covered without a separate policy through FEMA’s National Flood Insurance Program.

A third case, a sewer or sump pump backup, is covered only if you bought the water backup endorsement, which many older St. Louis Park and Hopkins homes need.

5

Does homeowners insurance cover mold?

Sometimes. Mold is covered only when it grows as a direct result of a covered water event, like that burst pipe, and only if you acted quickly to dry things out. If mold grew from a leak you ignored, it is excluded.

Many Minnesota policies also cap mold remediation at a set limit, often $5,000 to $10,000, so read your declarations page. The faster you call for water cleanup, the less likely mold is to start and the stronger your claim stays.

6

Does renters insurance cover water damage?

Renters insurance covers your belongings, not the building. If a pipe bursts in your Eden Prairie apartment and ruins your furniture, your renters policy pays for the contents, minus your deductible. The building structure is the landlord’s responsibility through their own policy. Like homeowners coverage, renters insurance excludes flooding and gradual leaks.

?

FAQ

Will filing a water damage claim raise my premium?

It can. A single claim may not, but multiple water claims in a few years can raise your rate or make renewal harder. For small losses close to your deductible, paying out of pocket is sometimes the better move.

How long do I have to file a water damage claim in Minnesota?

Report it as soon as you reasonably can. Policies require prompt notice, and waiting can be used to deny a claim. Document the damage with photos before cleanup, then call your insurer the same day.

Does insurance cover the cost of finding the leak?

Many Minnesota policies now include limited coverage for tearing out and replacing the wall or floor needed to reach a failed pipe. The repair of the pipe itself is still on you.

Should I call a restoration company or my insurer first?

Call both quickly. A restoration crew can start emergency drying right away to limit damage, which insurers expect you to do. When you call your insurance company, start with your agent rather than the claims department. Your agent knows your home and can help you read your policy, which tells you whether filing a claim beats paying directly.

Bedrock Restoration is experienced in settling claims and works directly with agents and adjusters from every major carrier in the Twin Cities. We document everything for your claim so you get the full scope of coverage you are entitled to, and mitigation and rebuild work that holds up.

What does the cleanup itself cost?

A typical Twin Cities water mitigation job runs about $4,600, and small losses can land under your deductible. Our plain-English cost guide breaks down the real numbers from nearly 200 local jobs.

The bottom line

  • Sudden and accidental water is covered; slow and neglected water is not
  • Outside flooding needs separate flood insurance through the NFIP
  • Sewer and sump backups need the water backup endorsement
  • Mold is covered only after a covered event, usually with a dollar cap
  • Insurance pays for the damage, not for the part that failed
  • Call fast: prompt action protects both your home and your claim

Water in your home right now?

When damage happens, you don’t have to face it alone. We answer our own phones, respond fast, and tell you what we find and what happens next. No call center. No runaround.

612-834-1501

The Bedrock Team

This guide is general information about typical Minnesota homeowners policies, not legal or insurance advice. Coverage, limits, and endorsements vary by carrier and by policy. Read your declarations page or call your agent to confirm what applies to your home.

Bedrock Restoration  ·  612-834-1501  ·  bedrockrestoration.com

The Restoration Gap: Why “Mitigation Only” Costs Minnesota Homeowners Thousands

Setting up industrial air movers and dehumidifiers for water damaged kitchen

A restoration gap is the window of time between when a pipe, sump pump, or dishwasher or ice-maker line fails and when cleanup actually begins. In most Twin Cities water damage events that gap stretches to two or three weeks — and the reason is structural. Mitigation companies can dry a house, but they can’t fix the pipe, pump, or line that caused the flood. A separate plumber has to come, diagnose, source parts, and complete the repair before drying equipment can be set. During that wait, mold grows, drywall wicks water upward, and insurance claims get complicated.

At Bedrock Restoration in St. Louis Park, MN, we close that gap. We are a licensed Minnesota general contractor with a Master Plumber on staff — meaning our team that arrives to extract the water will also shut off the leak, repair the source of the issue, and start the dry-down. One visit. One contract. One timeline.

What is the restoration gap and why does it exist?

The U.S. restoration industry grew up as a clean-up industry. Most national franchises — the household names on the yellow trucks — hold no plumbing license and no general contractor’s license. Their scope is narrow: extract water, set air movers, charge the insurance company.

That model can work temporarily on simpler leaks, when a dishwasher hose or toilet supply line can be shut off at the supply. But even then a plumber will need to be called in eventually. And that model falls apart completely when the source of the flood is still leaking — a hairline copper pinhole above a kitchen ceiling, a cracked PEX fitting behind a wall, a failed sump pump or water heater in a finished basement. In those cases mitigation technicians cannot legally repair the pipe. They tape off the area, tell the homeowner to call a plumber, and often leave the property until the plumbing work is done.

In St. Louis Park, Minnetonka, and Edina — markets with older housing stock and a high density of finished basements — that “wait for the plumber” phase runs 8 to 21 days once you account for emergency service backlogs, part availability, and the homeowner taking time off work to let two separate trades into the house.

The 48-hour mold clock doesn’t care about your calendar

The Institute of Inspection, Cleaning and Restoration Certification (IICRC) treats 48 hours as the standard threshold for microbial amplification in a wet building assembly. After that window, mold isn’t a risk — it’s a condition. Drywall becomes a Category 3 material. Baseboards and cabinet toe-kicks become disposable. Wet insulation has to be bagged out rather than dried.

The 48-hour mold clock starts the moment the water lands. It does not pause while you wait for a plumber.

A homeowner who loses a water heater on a Friday night, calls their insurance on Saturday morning, gets a mitigation referral on Monday, and schedules a plumber for Wednesday has already burned four days. At that point, the mitigation team that finally arrives isn’t drying a wet house — they’re demolishing a contaminated one. We see this pattern every week in the West Metro and Minneapolis: a repairable flood turns into a reconstruction job because the wrong team arrived first.

What the gap actually costs you

Three things get more expensive the longer the gap runs:

  1. Scope creep. Materials that could have been dried have to be replaced instead. A $6,000 mitigation claim becomes a $25,000 mitigation-plus-rebuild claim.
  2. Insurance complications. Adjusters look for “ongoing or repeated seepage” — a phrase used to deny claims. Every day water sits, the file looks more like a maintenance issue and less like a sudden event.
  3. A second deductible exposure. Some policies treat mold as a separate covered peril with its own sublimit, often $5,000 or $10,000. Homeowners who let mold bloom during the gap can exhaust that sublimit before demolition even starts.

Why most restoration companies can’t close the gap

There are real reasons the industry built itself this way, and they’re worth understanding so you can tell the difference between a full-service contractor and a rebrand.

Licensing. In Minnesota, repairing plumbing for hire requires a licensed plumbing contractor with a Master Plumber of record. Performing residential reconstruction work over $15,000 requires a residential building contractor license from the Minnesota Department of Labor and Industry. Each license carries its own continuing education, bonding, and insurance requirements. Most franchise restoration operators hold neither — they hold only mitigation-focused IICRC certifications.

Insurance and bonding costs. Carrying both GC and plumbing licenses roughly doubles a small company’s annual insurance and bonding expenses. The franchise model is optimized for volume and throughput; adding licensed trades cuts into that margin.

Workforce. Master Plumbers in the Twin Cities are among the hardest-to-hire trades in Minnesota. Hiring one full-time only makes sense if you have enough plumbing work to keep them busy between floods.

So the industry’s honest answer is: “We could do single-source — but it’s not what our model is built for.” Ours was built for it.

How the single-source model actually works on a job

When a Bedrock truck rolls into a flood in Edina, Minnetonka, Eden Prairie or Chanhassen, the same crew handles every step a two-trade sequence would handle — just without the handoff.

Hour 0–1: Stabilize and diagnose. Our plumber shuts off the source, isolates the failed component, and documents the cause of loss with photos that hold up in a claim. This step alone often saves homeowners a denial, because insurance carriers require proof that the failure was “sudden and accidental,” not gradual.

Hour 1–3: Repair the leak. Same crew, same visit. The pipe gets fixed before a single air mover is deployed. In most cases we restore domestic water service the same day — which matters when you have a family to feed and no running water.

Hour 3–8: Extraction and drying setup. IICRC-certified technicians extract standing water, remove contaminated materials under Category 2 and 3 protocols, and stage LGR (low-grain refrigerant) dehumidifiers and directed air movers. Every affected wall gets scanned with a moisture meter and a thermal imager, and the readings go into a daily moisture map the adjuster receives with the claim file.

Days 2–4: Monitored dry-down. Standard timeline for a single-room flood. Longer if the water traveled through floor assemblies or wall cavities.

Day 5 and beyond: Reconstruction. If materials have to be replaced, the same company that dried the house rebuilds it. No second bid, no starting over with the insurance adjuster. Our carpenters, drywall crew, and trades pick up where the mitigation crew left off.

The reconstruction advantage most mitigation companies leave on the table

Because our general contractor license lets us perform the rebuild, we quote both phases against the same Xactimate scope the adjuster is working from. That has two practical effects for homeowners.

First, there’s no “hand-off tax.” When two companies split a job, the reconstruction bidder has to re-measure, re-photograph, and re-estimate work the mitigation team already documented. Homeowners end up paying for that overlap — either directly or through a depleted claim.

Second, the rebuild often becomes an upgrade opportunity. If the walls are already open, the cost of adding a recessed light, relocating an outlet, or upgrading a cabinet run is a fraction of what it would cost as a standalone project. We walk every Bedrock client through what insurance will cover as “like kind and quality” and what they can add out of pocket at trade pricing. That conversation consistently saves our clients in St. Louis Park and the West Metro roughly 20–30% on post-flood improvements compared to starting a separate remodel a year later.

We cover that tradeoff in more depth in our guide on turning a water damage claim into an insurance-funded remodel.

What to ask any restoration company before you sign

If you want to avoid the restoration gap without hiring Bedrock, ask these four questions of any company on your adjuster’s preferred-vendor list:

  1. Do you hold a Minnesota residential building contractor license, and can you give me the license number?
  2. Is there a Master Plumber on your staff, or do you subcontract plumbing repair?
  3. If I hire you for mitigation, do you also rebuild?
  4. Who pays for the time between mitigation and reconstruction if it extends the mold window?

Any company worth hiring will answer those without hesitation. If the answer involves the phrase “we have trusted partners,” you are being sold a two-trade job.

Frequently asked questions

Does every water damage job need single-source service? No. If the source is already stopped — a one-time overflow from a tub, a washing machine supply hose that was caught and shut off — a mitigation-only company can handle the job. Single-source matters most when the leak is still active, hidden, or caused by a failed fixture that needs replacement before drying can begin.

Is a single-source restoration company more expensive? No. On the line-item invoice, the Xactimate pricing guide the carrier uses sets the ceiling. The savings show up in scope: less demolition, faster dry-down, and no overlapping charges between trades.

Does insurance cover the plumbing repair itself? Most homeowners policies in Minnesota cover the resulting damage from a sudden plumbing failure but exclude the failed component itself. The $200 pipe repair is on you; the $20,000 water damage is covered. Strong cause-of-loss documentation helps clients argue for the broadest possible interpretation of that line.

What service areas does Bedrock cover? Edina, Minnetonka, Chanhassen, Eden Prairie, St. Louis Park, Plymouth, Bloomington, Golden Valley, Hopkins, Minneapolis, and the rest of the West Metro area. We run 24/7 emergency dispatch with a Master Plumber on call. For local water damage response, see our St. Louis Park water damage restoration service page.

Call Bedrock at 612-834-1501 for a Truth-First Assessment.

The First 48 Hours After a Fire: A Homeowner’s Checklist

Fire damaged house with notepad for assessment

Nothing prepares you for what the first day after a house fire feels like. You’re standing in a hotel parking lot or a relative’s kitchen, you’ve slept maybe two hours, and your phone is filling up with calls from your insurance company, the fire marshal, and people you didn’t know existed yesterday. Everyone wants something from you. You can’t think straight enough to remember your own address.

This is the post we wish every Twin Cities homeowner had bookmarked before they needed it.

We’ve walked hundreds of families through this. The first 48 hours have a rhythm to them, and once you know what’s coming, the panic drops a notch. Below is exactly what to handle, in the order we’d handle it ourselves, organized so you can work through it without missing the things that matter most.

A note before you start. The single biggest decision in this window is which fire restoration company you hire, because that one choice determines whether you have an advocate on your side of the table for the next six to twelve months. We wrote a separate piece on that here: Should You Use the Fire Restoration Company Your Insurance Adjuster Recommends? Read it before you sign anything.

Now, the rest of the list.

Housing and Finances

The first practical question is where you’re sleeping tonight, tomorrow, and the next several months.

Set up Additional Living Expenses (ALE) with your insurer. Almost every homeowner’s policy includes ALE coverage. It pays for hotels, rentals, meals beyond your normal grocery spend, pet boarding, and anything else you’re paying for because you can’t live in your home. You have to formally activate it. Call your insurance company and say the words “I’d like to open my Additional Living Expenses coverage.” Ask what the daily or monthly cap is and how long it lasts.

Book temporary rental housing. Hotels are fine for a night or two, but a fire rebuild is a long road. Most jobs run four to nine months from loss to move-back. A furnished rental gives your family a kitchen, separate bedrooms, and a place to actually live. Look on Furnished Finder, Airbnb monthly stays, or call a local property manager who handles corporate relocations.

Keep every receipt. All of them. Meals, gas to and from the property, replacement clothing, toiletries, a phone charger because yours is in the house, the deposit on the rental, pet boarding, dry cleaning, everything. Most of it is reimbursable under ALE, but only if you have proof. Start a folder in your email and one on your phone for photos of paper receipts.

Write down your claim information. Claim number, adjuster’s full name, adjuster’s phone, adjuster’s email, deductible amount. Put it all in one note on your phone. You’ll be asked for these by every party involved, sometimes daily, for months.

Notify your mortgage company. They have a financial stake in your home and they need to know there’s been a loss. Insurance proceeds for the rebuild are usually issued in your name and the mortgage company’s name jointly. Calling them now prevents a paperwork mess later.

Contact your auto insurer if vehicles were involved. Auto and home are different policies and different claims. Don’t assume one adjuster handles both.

Communications and Service Changes

Your house is empty now, but the world doesn’t know that yet. Mail still arrives. Packages still get delivered. Subscriptions still bill.

Forward your mail. Go to USPS.com and set up a temporary mail forward to your rental address. It takes ten minutes.

Pause or cancel internet, cable, and any home utilities you can. No reason to pay for service at a damaged house. Most providers will pause your account for a month or two without penalty if you tell them what happened.

Update your address with delivery services. Amazon, UPS, FedEx, any subscription boxes. Otherwise packages pile up at the property and disappear.

Photograph the contents of your refrigerator and freezer before throwing food out. Most policies cover food spoilage as part of the contents claim. Open the doors, take a wide photo and a few close-ups, and keep a rough list of what was in there. Then throw it all out, the smell after a few days will be something you can never unsmell.

Notify your kids’ schools. Give them the temporary address and a note about pickup or drop-off if anything is changing. Teachers should know what’s going on, kids who’ve been through a house fire often need extra patience for a few weeks.

Tell your employer. You may need flexibility for adjuster meetings, contractor walk-throughs, contents pack-outs, and the general fog of the first month. Most employers will work with you, but only if they know.

Personal and Safety Items

The day after a fire, the fire department or your restoration crew will let you back into the house for a controlled walk-through. Do not try to enter alone, structural integrity, air quality, and electrical safety are real concerns.

When you do go in, here’s what to grab:

Prescription medications. All of them, for everyone in the household. If they’re in the kitchen or bathroom and the bottles are intact, take them. If they’re contaminated, take a photo of the label and call your pharmacy.

Eyeglasses, contacts, and medical devices. CPAP machines, hearing aids, blood pressure monitors, glucose monitors, mobility equipment. If you can’t find something or it’s damaged, call the manufacturer or your doctor for a replacement. Insurance contents claims usually cover this.

Call your pharmacy. Ask them to flag your account so refills aren’t interrupted, and update them with a new pickup location if you’ve moved across town.

Firearms. Locate every firearm in the house and store them off-site somewhere safe. A fire-damaged home with broken windows and a board-up is not secure. A relative’s gun safe, a friend’s house, or a paid storage solution all work.

Critical documents. Passports, birth certificates, social security cards, marriage license, deed to the house, vehicle titles, life insurance policies, wills. If your fireproof safe is intact and accessible, get it open. If it’s not safe to retrieve, it can wait, and most documents can be replaced.

One sentimental item per family member if it’s safe to grab it. A photo album. A wedding ring. A kid’s stuffed animal. After 48 hours of crisis logistics, having one familiar thing helps more than people realize.

Track Your Contacts in One Place

Over the next several months you will be asked for the same five pieces of information by every party involved. Adjusters, contractors, mortgage company, fire investigators, public adjusters, attorneys if it goes that direction. Save yourself the search.

Keep a single note or document with:
  • Fire report or incident number
  • Fire investigator’s name and phone number
  • Insurance adjuster’s name, phone, and email
  • Insurance claim number
  • Your restoration company’s project manager and direct line

We hand every Bedrock customer a printed version of this exact log on day one for this reason. Lost paperwork is one of the top causes of delays on fire claims, and the homeowner is usually the one paying for the delay in extra rental months.

What Comes Next

Once the first 48 hours are behind you, the pace changes. The fire investigation has to wrap, usually a few days to a few weeks. Your restoration company will move through bulk debris removal, then full demo, then mitigation, all gated by formal releases from the fire department, the police, and your insurance carrier. After mitigation comes the rebuild scope negotiation, then the rebuild itself.

A good restoration partner walks you through every release and every milestone, in plain language, so you always know what’s happening and what’s next.

You don’t have to figure this out alone.

If you’ve had a fire in the Twin Cities and you’re standing in the parking lot trying to figure out what to do next, call us. We answer 24/7, we’ll tell you what to handle in the next hour and what can wait until tomorrow, and we’ll be on-site within the hour if you need us.

The Bedrock Team 612-834-1501 service@bedrockrestoration.com

Should You Use the Fire Restoration Company Your Insurance Adjuster Recommends? Read This First.

Consultation of fire damaged house
When a fire tears through your home, you’re not thinking clearly. You’re standing in a driveway, your house is wrecked, and you want someone to take the problem off your plate. So when the insurance adjuster shows up and says, “Don’t worry, I’ll get a fire restoration company out here,” it feels like a relief.

We get it. We see this exact moment play out almost every week.

Here’s what every homeowner in the Twin Cities should understand before that moment arrives. The fire restoration company your adjuster brings out is not working for you. They’re working for the insurance company. And that distinction is going to cost you, sometimes in ways you won’t notice until months later when you’re staring at a mismatched paint line, cabinets that still smell like smoke, or a ceiling that should have been replaced instead of cleaned.

So here’s how the system actually works, plainly, so you can make the right call for your home.

What “Preferred Contractor” Actually Means

Insurance carriers run programs with names like Preferred Contractor Network, Managed Repair Program, or Direct Repair. The marketing makes it sound like a stamp of quality. It isn’t. It’s a contract.

To get on those programs, fire restoration companies agree to specific terms. The terms vary by carrier, but the pattern is consistent.

The contractor agrees to follow the adjuster’s scope of work without pushback. The contractor agrees to specific pricing, often below market rate. The contractor agrees not to dispute the adjuster’s findings on coverage or scope. In exchange, the contractor receives a steady flow of leads.

Read that again. The contractor agrees not to push back on the adjuster. That’s the deal. That’s why they’re on the list.

So when an adjuster says “I have a great company I work with,” what they’re really saying is “I have a company that will not challenge me on anything.”

That works great for the insurance company. It does not work great for you.

What This Costs You on Fire Mitigation

Fire mitigation is the emergency work in the first one to two weeks after the loss. Board-up, soot removal from structure and contents, smoke odor treatment, HVAC cleaning, demo of unsalvageable materials, contents pack-out and inventory.

A program contractor’s job is to do the minimum scope the adjuster approves. If the scope says clean the soot off the framing, they clean the framing, even when the soot has penetrated the wood and the right call is to remove and replace. If the scope says ozone the contents, they ozone, even when the right call is replacement. If the scope says clean the ductwork, they clean it, even when the system needs to come out.

An independent contractor’s job is different. We assess the loss based on what the IICRC fire and smoke restoration standard says should happen, document it with photos, soot testing, and written justification, and tell the adjuster what’s required. If we disagree with the scope, we say so on the record.

The difference shows up six months later when the smoke smell comes back every time the furnace kicks on. Or when the framing keeps off-gassing through fresh drywall. Or when your kid’s bedroom still smells like a campfire.

What This Costs You on the Rebuild

This is where the real money disappears.

Fire rebuild is the put-back work, and on a fire job it’s massive. New framing, drywall, insulation, paint, flooring, cabinets, trim, fixtures, electrical, sometimes structural. The scope is enormous and so is the room for the insurance company to save money at your expense.

Here’s a short list of what we routinely see program contractors accept on fire claims that we would fight.

Painting only the affected rooms instead of the connected open-concept space, leaving you with visible color lines where one room meets the next. Cleaning smoke-damaged cabinets instead of replacing them. Sealing sooted framing instead of removing it. Refinishing hardwood that should be torn out and replaced. Using a builder-grade material when the original was higher end. Skipping trim, baseboards, and crown molding that absorbed smoke. Not replacing insulation that holds odor for years. Patching ceilings instead of replacing full sheets, leaving texture mismatches you’ll see every time you walk into the room. Reusing HVAC equipment that should be replaced.

Every one of those is a fight an independent contractor has with adjusters all the time. We win most of them because we document everything and we know the policy language. A program contractor cannot have that fight. It’s against the agreement they signed.

The “I Already Have Someone” Conversation

This is the moment we want to change.

Adjuster shows up. Tells the homeowner they’ll send out their guy. Their guy arrives, hands the homeowner a piece of paper to sign, and starts work. Homeowner thinks they made a choice. They didn’t. The adjuster made the choice for them.

Then we get a call from a neighbor, a firefighter, or a referral, and the homeowner says “I already have someone.” We ask who. They tell us. And we already know how that job is going to go.

You are allowed to choose any licensed fire restoration company you want. Your insurance policy does not require you to use the adjuster’s recommendation. It does not require you to use anyone on a preferred list. That’s your home, your claim, and your money. You pick.

What an Independent Fire Restoration Company Actually Does

Bedrock does zero program work. We are not on any preferred contractor list. That’s not an accident, it’s the business model.

When you sign with us, here’s what changes.

We dictate the scope based on what your home actually needs, then we present it to the adjuster. We push back, in writing, when the adjuster wants to cut corners. We document with photos, soot testing, thermal imaging, and written reports so the file is bulletproof. We handle the entire claim communication so you’re not on the phone fighting with your carrier while you’re trying to figure out where your family is sleeping next week. We do fire mitigation and rebuild under one roof, so nothing falls through the cracks between phases. We answer when you call. Not a call center, our team.

We get paid the same whether the scope is small or large. Our incentive is to do it right, document it, and stand behind the work. The insurance company does not control our pricing, our scope, or our reputation.

What to Do in the First 24 Hours After a Fire

Take a breath. Nothing has to happen in the next ten minutes.
Then:
  1. Document the damage yourself with your phone. Photos and video of every room, every angle, before anything is moved.
  2. Call two or three independent fire restoration companies. Ask them directly, “Are you on any insurance preferred programs?” If the answer is yes, keep calling.
  3. Do not sign anything the adjuster’s contractor hands you until you’ve talked to at least one independent option.
  4. Once you choose your company, let them handle the adjuster relationship from that point forward.

The companies that show up fast and answer the phone are usually the ones who’ll take care of you. The ones who hand you a clipboard and tell you to sign before they start work are usually the ones with a deal in place somewhere.

Once you’ve picked your contractor, there’s a longer list of housing, financial, and personal items to handle in the first day or two. We put together a full walkthrough here: The First 48 Hours After a Fire: A Homeowner’s Checklist.

The Bottom Line

Your insurance company is a business. Their job is to settle your claim for as little as possible. The adjuster is good at their job. The preferred contractor is good at theirs. Both jobs involve protecting the insurance company’s bottom line.

You need someone on your side of the table. That’s the whole point of hiring an independent fire restoration company. Not because we’re nicer or because we have a fancier truck. Because the contract we sign is with you, not with them.

If you’ve had a fire and an adjuster has already named a contractor, call us before you sign anything. We’ll tell you straight whether you need us or not.
The Bedrock Team 612-834-1501

Can I file an insurance claim for wind damage to my Edina roof?

Aging asphalt shingles with storm debris

Yes, wind damage is typically covered under homeowners insurance policies, including lifted, creased, or missing shingles. Document the damage with photos immediately and contact your insurance company, as wind storms in the West Metro can cause significant roof damage that qualifies for claims. Most standard policies in Edina and surrounding Minneapolis communities include wind damage coverage, making it possible to repair or replace storm-damaged roofing without bearing the full cost yourself.

Understanding Wind Damage Coverage in Minnesota

Homeowners insurance policies in Minnesota generally include wind and hail damage as part of standard coverage. This protection is particularly important in the Minneapolis West Metro area, where severe summer storms can generate straight-line winds exceeding 60 mph, creating substantial roof damage across communities like Edina, St. Louis Park, Minnetonka, and Hopkins.

Wind damage coverage typically includes shingles that have been torn off, lifted, creased, or damaged by flying debris. It may also cover damage to flashing, gutters, vents, and other roofing components. For Edina homeowners with older homes from the 1940s-1960s era—common throughout the established neighborhoods—wind damage can be especially problematic if the roof was already nearing the end of its lifespan.

What Qualifies as Covered Wind Damage

Insurance companies typically cover wind damage when it results from a sudden weather event rather than gradual deterioration. Qualifying damage includes:

Shingle damage: Missing shingles, lifted tabs, creased or cracked shingles, or granule loss from wind abrasion

Structural damage: Damage to roof decking, rafters, or trusses caused by falling branches or severe uplift

Secondary damage: Water infiltration resulting directly from wind damage that compromised the roof’s integrity

Debris impact: Damage from tree limbs, patio furniture, or other objects propelled by wind

Insurance adjusters distinguish between storm damage and normal wear-and-tear. A roof with pre-existing deterioration may still qualify for coverage if new wind damage is clearly identifiable and documented.

Steps to File a Wind Damage Claim in Edina

Taking prompt action after discovering wind damage maximizes your chances of claim approval and prevents secondary damage like water infiltration.

1. Document the Damage Immediately

Take comprehensive photographs and videos of all visible damage from ground level and, if safely accessible, closer views. Capture wide shots showing the overall roof condition and close-ups of specific damaged areas. Photograph any debris, fallen branches, or other evidence of the storm’s impact.

Document interior damage as well, including water stains, ceiling damage, or insulation issues that resulted from the wind damage. This evidence establishes the connection between the exterior damage and interior problems.

2. Arrange for Temporary Repairs

Most insurance policies require you to mitigate further damage. Cover exposed areas with tarps if possible, but prioritize safety—don’t attempt roof access during dangerous conditions or if you’re uncomfortable with heights. Professional roofing contractors like Bedrock Restoration offer emergency tarping services throughout the West Metro to prevent water damage while your claim is processed.

Keep all receipts for temporary repairs, as these costs are typically reimbursable under your policy.

3. Contact Your Insurance Company

Report the damage to your insurance company as soon as possible. Provide them with the documentation you’ve gathered and a detailed description of the storm event, including the date and approximate time. Your insurer will assign an adjuster to inspect the damage and determine coverage.

4. Schedule a Professional Roof Inspection

Have a qualified roofing contractor inspect your roof before the insurance adjuster arrives. A professional inspection from a company familiar with Minnesota weather patterns can identify all storm-related damage, including less obvious issues like compromised flashing or damaged decking. This ensures nothing is overlooked during the claims process.

Many Edina homeowners find it beneficial to have their roofing contractor present during the insurance adjuster’s visit to provide technical expertise and ensure accurate damage assessment.

Working with Insurance Adjusters

Insurance adjusters evaluate damage to determine what repairs your policy will cover. Understanding this process helps you advocate effectively for your claim.

Adjusters assess whether damage resulted from a covered peril (like wind) versus normal aging. For homes in Golden Valley, Plymouth, Eden Prairie, and surrounding areas with asphalt shingles installed 15-20 years ago, this distinction becomes particularly important. Clear documentation of the storm event and visible new damage helps establish your claim’s validity.

If your adjuster’s assessment seems incomplete, you have the right to request a re-inspection or obtain an independent assessment. Roofing contractors experienced with insurance claims can provide detailed reports that support your position.

Minnesota-Specific Considerations for Wind Damage

The Minneapolis West Metro experiences unique weather challenges that affect wind damage claims:

Extreme temperature fluctuations: Minnesota’s temperature swings from -20°F to 95°F create stress on roofing materials, sometimes making them more vulnerable to wind damage during summer storms.

Ice dam complications: Wind damage during winter months may be complicated by existing ice dam issues. Adjusters need to distinguish between these separate problems.

Hail combinations: Many summer storms in Minnetonka, Hopkins, and surrounding communities include both wind and hail. Comprehensive damage assessment should identify all storm-related issues.

Architectural shingle performance: Most homes in St. Louis Park, Edina, and Richfield use architectural shingles rated for high winds, but older installations may not meet current standards.

Choosing Impact-Resistant Shingles for Replacement

If your claim is approved for roof replacement, consider upgrading to Class 4 impact-resistant shingles. These products offer superior protection against hail and wind damage—both common in Hennepin County—and many insurance companies provide premium discounts of 10-30% for impact-resistant materials.

This upgrade is particularly valuable in areas like Maple Grove, Brooklyn Park, and Bloomington, where severe weather frequency justifies the additional investment in durable roofing materials.

Get Expert Help with Your Edina Wind Damage Claim

Filing an insurance claim for wind damage doesn’t have to be overwhelming. Bedrock Restoration has extensive experience helping homeowners throughout Edina, St. Louis Park, Minnetonka, Hopkins, and the entire Minneapolis West Metro navigate the insurance claims process. Our team provides thorough damage assessments, works directly with insurance adjusters, and delivers quality repairs that restore your roof’s integrity.

Contact Bedrock Restoration today at https://bedrockrestoration.com for a free roof inspection and expert guidance on your wind damage insurance claim. We’ll help you document the damage, communicate effectively with your insurer, and restore your roof to optimal condition.

How often should I replace my roof in the Minneapolis area?

Snow-covered roof ridge at sunset overlooking a city skyline during winter

Most asphalt shingle roofs in the Minneapolis West Metro last 20-25 years under normal conditions, though Minnesota’s extreme weather can significantly impact this timeline. Factors like proper attic ventilation, installation quality, storm damage from hail and ice dams, and our severe freeze-thaw cycles all play crucial roles in determining when replacement becomes necessary. Rather than waiting for a specific timeframe, homeowners in St. Louis Park, Minnetonka, Hopkins, Edina, and surrounding communities should have their roofs professionally inspected every 3-5 years and after major weather events.

Understanding Roof Lifespan in Minnesota’s Harsh Climate

The Minneapolis area presents unique challenges that differentiate our roofing needs from national averages. While asphalt shingle manufacturers often advertise 30-year warranties, the reality in communities like Golden Valley, Plymouth, and Eden Prairie is that few roofs reach that age without significant issues.

Our climate subjects roofs to temperature swings from -20°F in January to 95°F in July—a 115-degree variance that causes expansion and contraction cycles throughout the year. This constant movement breaks down roofing materials faster than in more temperate regions. Add frequent hail storms, heavy snow loads exceeding 40 pounds per square foot, and destructive ice dams, and you’ll understand why Minnesota roofs age faster than those in milder climates.

Signs Your Roof Needs Replacement

Visible Shingle Damage

Curling, cupping, or missing shingles are clear indicators your roof is nearing the end of its serviceable life. In neighborhoods throughout Hennepin County with 1950s-1960s ramblers and split-levels, we frequently see granule loss creating bald spots on shingles. These granules protect the asphalt from UV damage, and once they’re gone, deterioration accelerates rapidly.

Interior Warning Signs

Water stains on ceilings, particularly in Wayzata, Maple Grove, and Bloomington homes, often indicate compromised roofing. Attic inspections revealing daylight through roof boards, moisture accumulation, or sagging decking all signal urgent attention is needed.

Age-Related Concerns

If your roof is approaching 20 years old and you’re experiencing minor issues, replacement typically makes more financial sense than ongoing repairs. Many of our established West Metro neighborhoods contain homes with original roofs from the 1990s or early 2000s that are now due for replacement.

Factors That Shorten Roof Lifespan in Our Region

Storm Damage

Minnesota ranks among the top states for hail damage claims. The severe storms that sweep through Brooklyn Park, Richfield, and surrounding areas can shave years off a roof’s expected lifespan in a single afternoon. Even if damage seems minor, hail impacts weaken shingle integrity and create entry points for moisture.

Ice Dam Formation

Our freeze-thaw cycles create perfect conditions for ice dams along roof edges. These ice accumulations force water underneath shingles, damaging underlayment and decking. Homes in Hopkins, St. Louis Park, and Edina with inadequate attic insulation or ventilation face this problem repeatedly, leading to premature roof failure.

Poor Ventilation and Insulation

Many mid-century homes throughout the West Metro were built with minimal attic ventilation. Without proper airflow, summer heat builds up in attic spaces, literally cooking shingles from underneath and significantly reducing their lifespan. Winter condensation from inadequate insulation creates moisture problems that rot decking.

Extending Your Roof’s Service Life

Regular Professional Inspections

Schedule inspections every 3-5 years and after significant weather events. These preventative assessments catch minor issues before they become major problems requiring full replacement.

Prompt Repairs

Address damaged or missing shingles immediately. In Minnesota’s climate, small problems escalate quickly when moisture penetrates the roofing system.

Proper Attic Ventilation

Ensure your attic maintains proper airflow. This protects shingles from excessive heat and prevents winter ice dam formation—two leading causes of premature roof failure in our area.

Consider Upgraded Materials

When replacement time arrives, consider Class 4 impact-resistant shingles. These products resist hail damage better than standard shingles and often qualify for insurance discounts. Metal roofing is also gaining popularity in Eden Prairie, Plymouth, and other West Metro communities for its longevity and superior snow-shedding capabilities.

Working With Insurance After Storm Damage

Many Minneapolis-area homeowners don’t realize that storm damage may be covered by their insurance policy. If you’ve experienced hail, high winds, or ice dam damage, document the damage with photos and contact your insurance company. Professional roofing contractors experienced in working with adjusters can help ensure you receive fair compensation for legitimate claims.

Schedule Your Free Roof Inspection Today

Don’t wait for leaks to appear before assessing your roof’s condition. Bedrock Restoration provides comprehensive roof inspections throughout St. Louis Park, Minnetonka, Hopkins, Edina, and the entire Minneapolis West Metro. Our team understands the unique challenges Minnesota weather presents and can help you determine whether repair or replacement is the right choice for your home. Contact us today at https://bedrockrestoration.com to schedule your free inspection and protect your home’s most important defense against our extreme climate.

How Much Will Water Damage Restoration Will Cost?

You won’t know the full cost immediately—and that’s actually a protection, not a problem. The insurance company and restoration company work together to approve the scope of work, and pricing follows regulated industry standards using estimating software called Xactimate. This process ensures you’re never billed for work that wasn’t justified, documented, and approved.

Understanding how this system works helps you trust the process even when exact numbers aren’t available on day one.

Why You Won’t Know the Full Cost Immediately

Water damage pricing can’t be determined instantly because the full scope isn’t visible right away. But beyond that practical reality, a system exists specifically to protect you from arbitrary or inflated pricing.

The process is designed for fairness. Rather than restoration companies inventing prices, the industry uses standardized pricing databases that reflect fair market rates for every task, material, and labor hour.

Multiple parties verify the scope. Your insurance adjuster reviews what the restoration company proposes, ensuring the work is necessary and priced appropriately. This creates accountability.

Documentation drives everything. Every line item must be justified with evidence—moisture readings, photos, measurements. You won’t pay for anything that can’t be documented and explained.

Homeowners in Minneapolis, Eden Prairie, and St. Louis Park benefit from this system even though it takes time, because it prevents both underestimating (leading to incomplete work) and overestimating (leading to unnecessary costs).

How Restoration Pricing Actually Works

The pricing process follows a predictable sequence:

Step 1: Assessment and documentation. Technicians document all damage with photos, moisture readings, and detailed notes. This creates the factual foundation for pricing.

Step 2: Scope development. Based on documentation, the restoration company creates a detailed scope of work listing every task required—water extraction, equipment placement, material removal, drying time, repairs needed.

Step 3: Estimate creation. Using industry-standard software, the company generates an estimate with line-item pricing for each task. Every price comes from a database, not guesswork.

Step 4: Insurance review. Your adjuster reviews the estimate against the documentation. They may approve it as submitted, request clarification, or negotiate specific line items.

Step 5: Approval and work authorization. Once scope and pricing are agreed upon, work proceeds with clear expectations. If additional damage is discovered, a supplement process captures those costs with the same documentation and approval steps.

This collaborative process takes time but ensures everyone agrees on what’s being done and what it costs.

What Is Xactimate and Why Does It Matter

Xactimate is the industry-standard software used by most insurance companies and restoration contractors nationwide. Understanding it helps you see why pricing isn’t arbitrary:

Standardized pricing database. Xactimate contains prices for thousands of specific tasks—removing a square foot of drywall, running an air mover for a day, installing carpet padding. These prices are researched and updated regularly to reflect actual market rates.

Geographic adjustments. Prices adjust based on location. Labor and material costs in Minnetonka differ from costs in rural Minnesota. Xactimate accounts for these regional differences.

Line-item transparency. Every charge appears as a separate line item with quantity, unit price, and description. Nothing is hidden in vague categories.

Insurance companies use it too. When your adjuster reviews an estimate, they’re often using the same software. This creates a common language and reduces disputes.

Industry acceptance. Because Xactimate is standard, pricing doesn’t vary wildly between reputable companies. A legitimate restoration company in Edina should produce similar estimates to one in Bloomington for the same scope of work.

This standardization protects you from both overcharging and from companies that underbid then cut corners.

The Approval Process That Protects You

Multiple checkpoints exist before you owe anything:

Before mitigation begins: Emergency work starts immediately to prevent further damage, but even this is documented and priced according to standards. Insurance expects and covers reasonable mitigation costs.

Before major repairs begin: Reconstruction estimates require insurance approval before work starts. You’ll know what’s covered and what your responsibility is before committing.

When scope changes: If technicians discover additional damage during the project, they document it and submit a supplement request. Insurance reviews this addition before the work is billed.

Before final payment: You receive itemized invoices showing exactly what was done. Every charge traces back to documented work and approved scope.

Homeowners in Chanhassen, Plymouth, and throughout the Twin Cities can review documentation at any point and ask questions about any line item.

What You’ll See Before Paying Anything

Transparency should be standard throughout the process:

Initial assessment summary. A clear explanation of damage found, areas affected, and preliminary scope. This sets expectations even before detailed pricing.

Detailed estimate with line items. Every task listed separately with quantities and pricing. You can see exactly what you’re paying for—not just a lump sum.

Insurance communication. Updates on what insurance has approved, any items under discussion, and how your deductible applies.

Change documentation. If scope expands, written explanation of what changed and why, with corresponding estimate updates.

Final invoice matching approved scope. The bill should align with what was approved. No surprise charges for undiscussed work.

Ask questions if anything is unclear. Reputable companies explain their pricing because they have nothing to hide.

Red Flags in the Pricing Process

Watch for these warning signs that suggest problems:

  • Lump-sum quotes without line items: You can’t verify fair pricing without detail
  • Pressure to pay before insurance review: Standard process involves insurance coordination
  • Estimates that don’t use industry-standard software: May indicate inflated or arbitrary pricing
  • Unwillingness to explain charges: Every line item should be explainable
  • Charges for work not discussed or documented: You should recognize everything on the invoice
  • Dramatically different pricing than insurance approved: Legitimate supplements follow a process
  • Demands for large upfront payments: Some deposit may be reasonable, but most payment follows work completion

Questions to Ask About Pricing

Get comfortable with the process by asking:

  1. “Do you use Xactimate for estimates?” Industry-standard software indicates professional practices.
  2. “How does the insurance approval process work?” Look for clear explanation of collaboration with adjusters.
  3. “Will I see line-item pricing before work begins?” Transparency should be standard.
  4. “How do you handle additional damage discovered during the project?” Supplement processes should be explained clearly.
  5. “What happens if insurance doesn’t cover something?” Understanding potential gaps helps you plan.

The Bottom Line: A System Protects You

Industry standards ensure fair pricing:

  • Xactimate provides regulated, market-based rates
  • Line-item estimates show exactly what you’re paying for
  • Geographic adjustments reflect local costs

Approval processes prevent overcharging:

  • Insurance reviews scope and pricing
  • Documentation justifies every charge
  • Supplements require separate approval

Transparency is your right:

  • Ask questions about any line item
  • Request documentation supporting charges
  • Review estimates before authorizing work

You won’t know the exact cost on day one, but the system ensures you’ll understand and approve costs before you pay them.

Next Steps for Twin Cities Homeowners

If you’re facing water damage in Minneapolis, Wayzata, Savage, or anywhere in the metro area, trust the process even when immediate answers aren’t available.

Work with a restoration company that uses industry-standard pricing, communicates openly with your insurance company, and provides transparent documentation throughout. The right partner ensures you understand every dollar before it’s billed.


Why Can’t a Restoration Company Give Me a Quote Right Away?

Because too much is unknown before proper assessment. Asking for an exact quote before inspection is like asking a doctor how much knee surgery will cost before they’ve done x-rays. There’s critical information that can only be gathered through testing, time, and careful evaluation. Restoration companies need to discover what materials are wet, how far water traveled, and what can be saved versus what must be replaced.

This isn’t evasion—it’s honesty about how water damage actually works.

The Doctor Analogy: Diagnosis Before Treatment

The medical comparison is apt because water damage restoration follows a similar process:

Initial exam. The doctor looks at your knee, asks questions, and identifies obvious issues. A restoration technician walks through your home, notes visible damage, and takes preliminary moisture readings.

Testing and imaging. X-rays and MRIs reveal what’s happening inside—damage invisible to the naked eye. Moisture meters, thermal imaging, and inspection behind walls reveal how far water actually traveled.

Diagnosis develops over time. Sometimes the doctor discovers additional problems during treatment. Similarly, opening walls or lifting flooring sometimes reveals damage that wasn’t apparent initially.

Treatment plan adjusts accordingly. The final scope and cost become clear only after full assessment. Rushing to a price before understanding the problem leads to either underestimating (and surprise bills later) or overestimating (and unnecessary work).

Homeowners in Minneapolis, Eden Prairie, and St. Louis Park benefit from companies that take assessment seriously rather than guessing at prices.

What’s Unknown on Day One

When a restoration company first arrives, they can see some things but not others:

Visible on arrival:

  • Standing water on floors
  • Obvious wet carpet or flooring
  • Water stains on walls or ceilings
  • The general affected area

Hidden until testing:

  • How high moisture wicked up inside walls
  • Whether water reached adjacent rooms through hidden paths
  • Moisture levels in subfloor beneath flooring
  • Saturation depth in structural materials
  • Condition of insulation inside wall cavities

Unknown until drying begins:

  • Which materials can be dried in place versus removed
  • Whether hardwood floors will stabilize or require replacement
  • Total equipment needs and drying duration
  • Hidden mold or damage behind surfaces

Water is deceptive. A wet spot on your ceiling might trace back to a bathroom two rooms away. A damp baseboard might indicate saturation three feet up inside the wall. These discoveries happen through systematic assessment, not guesswork.

How the Discovery Process Works

Professional restoration companies follow a methodical approach to understand your damage:

Day one: Initial assessment. Technicians document visible damage, take preliminary moisture readings at multiple points, identify the water source, and categorize the water type (clean, gray, or contaminated). This provides enough information for a rough estimate range.

Days one through three: Detailed moisture mapping. Using specialized meters and thermal imaging, technicians map exactly where moisture exists throughout affected areas. This reveals the true scope—often larger than what’s visible.

During drying: Ongoing discovery. As equipment runs and materials dry, additional information emerges. Walls opened for airflow may reveal unexpected damage. Flooring behavior during drying indicates whether it’s salvageable. Moisture readings track progress and confirm when drying is complete.

After drying: Final scope confirmation. Only when everything is dry and exposed can accurate repair estimates be generated. Now technicians know exactly what needs replacing and can price accordingly.

Homeowners in Minnetonka, Edina, and Bloomington who understand this process have realistic expectations about estimate timing.

When You Can Expect Accurate Pricing

Different phases allow for different pricing accuracy:

Immediately (day one):

  • Rough ballpark range based on visible damage
  • General magnitude (minor, moderate, severe)
  • Not reliable for budgeting purposes

Within 24-48 hours:

  • Reasonably accurate mitigation estimate
  • Equipment needs and expected duration
  • Material removal scope

After drying completes (days 5-10):

  • Accurate repair and reconstruction estimates
  • Specific material and labor costs
  • Final project pricing

After insurance review:

  • Confirmed coverage amounts
  • Any gaps between estimate and approved scope
  • Final out-of-pocket expectations

Rushing this timeline produces unreliable numbers. A company quoting exact costs on day one is either guessing or planning to adjust later.

What Reputable Companies Tell You Upfront

Honest restoration companies communicate clearly about what they know and don’t know:

What they should tell you early:

  • Preliminary assessment of damage severity
  • Estimated range for mitigation costs
  • Expected timeline for drying
  • When more accurate pricing will be available
  • How they’ll communicate as scope develops

What they shouldn’t claim to know:

  • Exact final project cost before assessment
  • Precise repair pricing before drying completes
  • Guaranteed timelines before seeing full scope
  • Whether insurance will cover everything

Transparency about uncertainty is actually a sign of professionalism. Companies that acknowledge unknowns upfront are less likely to surprise you later.

Red Flags: Companies That Quote Immediately

Be cautious of companies that provide exact pricing too quickly:

  • Firm quotes before inspecting the property: Impossible without seeing the damage
  • Exact final costs on day one: No one can know this before assessment
  • “We’ll figure out the price later”: Vague promises lead to disputes
  • Dramatically lower quotes than competitors: May indicate corners being cut or change orders coming
  • Pressure to sign contracts before assessment completes: Protects them, not you
  • Unwillingness to explain their pricing process: Transparency should be standard

A company that seems to have all the answers immediately either has done this exact situation hundreds of times (unlikely, since every home differs) or is telling you what you want to hear rather than what’s true.

Homeowners in Chanhassen, Plymouth, and throughout the Twin Cities should value honest uncertainty over false confidence.

Questions to Ask About the Estimate Process

Get clarity on how pricing will develop:

  1. “What can you tell me today about likely costs?” Expect ranges, not exact figures.
  2. “When will I have a firm mitigation estimate?” Should be within 24-48 hours.
  3. “How will you communicate if scope changes?” Look for clear processes, not vague assurances.
  4. “When will accurate repair pricing be available?” After drying completes is the honest answer.
  5. “What factors might increase the final cost?” Honest companies discuss variables proactively.

The Bottom Line: Discovery Takes Time

Day one provides:

  • General damage assessment
  • Rough cost ranges
  • Understanding of scope magnitude

The following days reveal:

  • True extent of moisture spread
  • What’s salvageable versus replaceable
  • Accurate mitigation costs

After drying shows:

  • Complete repair requirements
  • Final material and labor pricing
  • Reliable project budgets

Patience pays off:

  • Accurate estimates prevent surprises
  • Proper assessment ensures complete restoration
  • Honest timelines build trust

Next Steps for Twin Cities Homeowners

If you’re dealing with water damage in Minneapolis, Wayzata, Savage, or anywhere in the metro area, expect the pricing process to unfold over days, not hours.

Work with a company that explains what they know, acknowledges what they don’t, and keeps you informed as the full picture develops. The right partner values accuracy over speed—because getting it right matters more than giving you a number you want to hear.