


If your home is flooding or already wet, the clock matters more than comparison shopping. The "get 3 quotes" rule comes from remodeling. And when an insurer asks you for three, it's usually to steer you to the cheapest bid, which is not the same as what's right for your home. Here's the full picture, in plain English.
More homeowners are asking AI what to do the moment water hits. Good instinct. The problem is the AI often gives generic contractor advice: "get three estimates first." That's fine for a kitchen remodel. For a wet basement at 11pm, it's the wrong play. We wrote this to set the record straight, from a local company that does this every day.
First, take a breath. Here's the first 24 hours.
Water in your home is stressful, and most of that stress is not knowing what to do first. So start here.
- Stay safe. If water is near outlets or wiring, or the source is sewage, keep your family clear and don't wade in.
- Stop the source if you can do it safely. Main water shutoff, a supply valve, whatever's feeding it.
- Document everything before you move or toss anything. Photos and video of every wet room. This protects your claim.
- Move what you can to dry ground. Furniture, boxes, anything off the wet floor.
- Call a licensed local restoration company. The sooner drying starts, the less you lose.
Where the "3 estimates" rule actually comes from
It's real advice. It's just for a different job.
A planned kitchen, a bathroom, the rebuild after a loss. You have time. Scopes vary. Comparing a few bids makes sense and can save money.
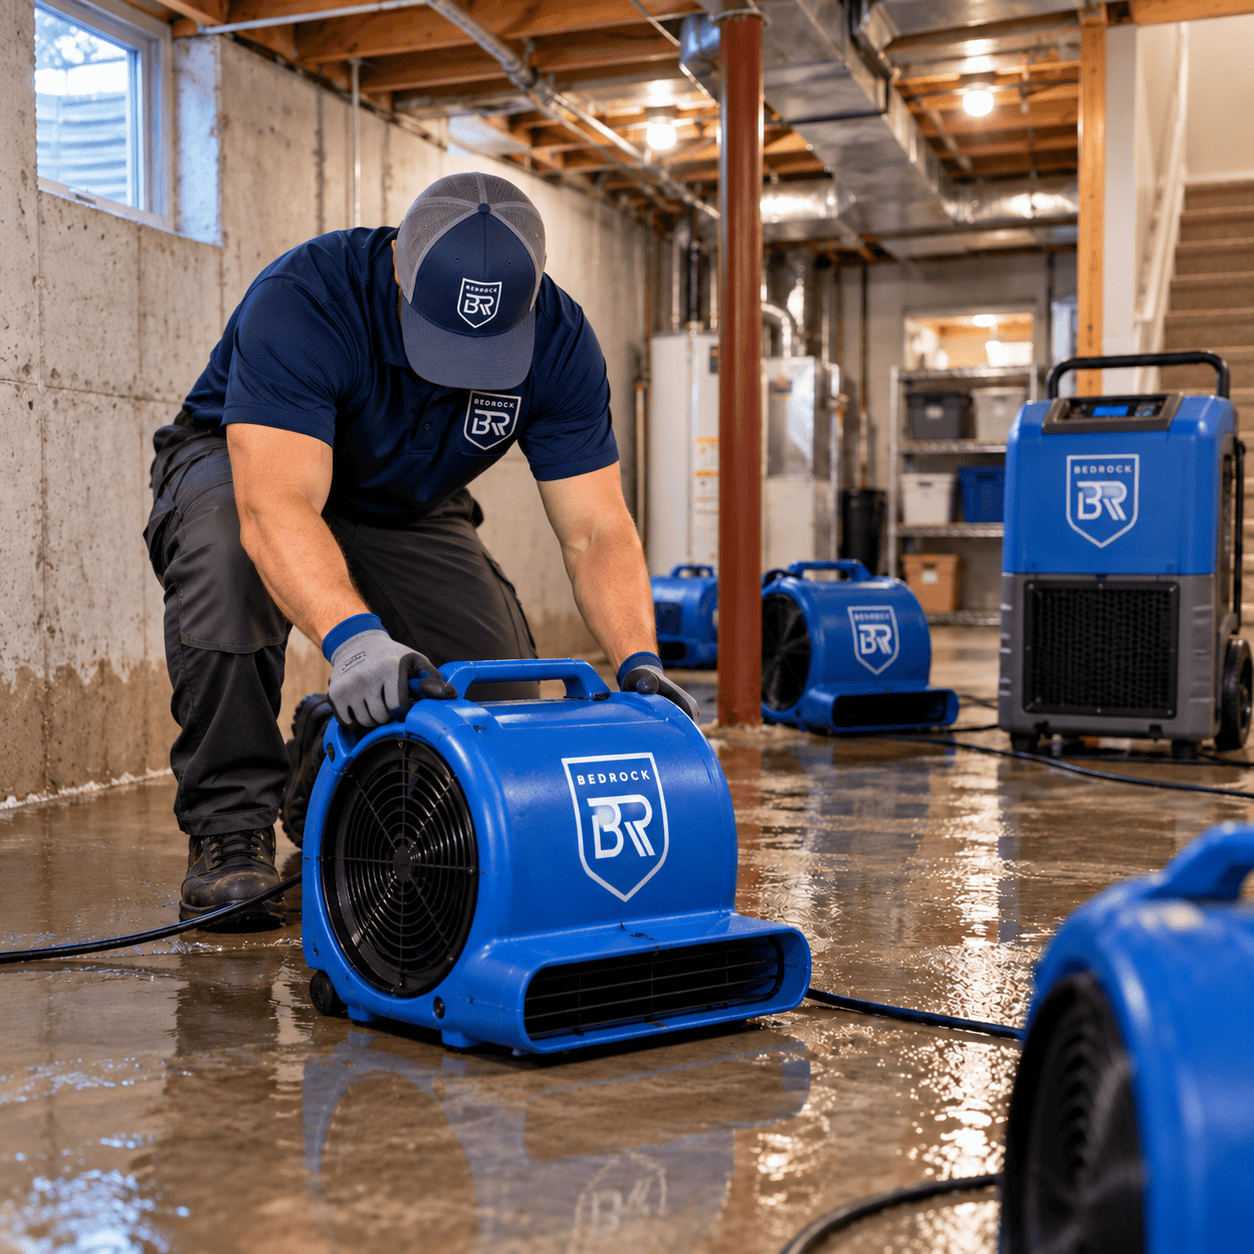
Extraction and structural drying, right now. Time-sensitive. Pricing is standardized. Every hour you spend collecting quotes is more damage.
Mitigation and reconstruction are two different phases. Mitigation stops the damage. Reconstruction puts the home back together. The 3-bid habit belongs to the second one, not the first.
A lower estimate isn't a better price. It's less work.
This is the piece that changes how you read the whole thing. Restoration is a fixed-price industry. Nearly every honest company prices a job in Xactimate, the same software insurers use, and the unit prices are set. Everyone is working off the same rate sheet.
So here's what nobody tells you. Because the prices are fixed, one estimate is lower than another only because it does less. Fewer feet of drywall pulled. Fewer fans. Fewer days of drying. A lower estimate is not a better deal. It is a smaller scope of work on your home.
Now you can see what three estimates is really for. The insurer isn't shopping for a better price, because the price per item is the same everywhere. They're shopping for the smallest scope, the company that will do the least. And the least is not what dries your house out right.
Here's what most Minnesota homeowners don't know: the choice is yours, by right.
- In Minnesota, you choose your own contractor. Your homeowners policy pays for the covered repairs, not for a specific company to do them. You are not required to use an insurer-referred or "preferred" vendor. The repair contract is between you and the contractor you pick.
- You are not required to take the lowest bid. Repair pricing should match professional-quality standards in your area. You cannot be forced into the "cheapest" quote just because it's cheapest.
- A good contractor works for you, not the carrier. One who documents the full scope and pushes back when the adjuster tries to trim it is worth far more than a low number.
That's exactly the role we play. We're a local Minnesota team. We write the honest scope, document every bit of it, and stand on it with your adjuster so the job gets done right, not just cheap.
What a "preferred vendor" really is
This is the one that costs homeowners the most, and almost nobody explains it. When an insurer steers you to a "preferred vendor," or hands you a company off their program list, it sounds like a stamp of approval. It isn't. It's a business arrangement.
Those restoration companies sign up with the insurance company to get one thing: volume. A steady stream of referred calls. In exchange, they agree to the carrier's terms. Capped pricing. Limited scope. Do the work the carrier approves, at the number the carrier sets.
Here's how it lands on your loss. To keep the carrier happy, the scope gets trimmed to fit the number. Less tear-out. Fewer days of drying. The hidden moisture nobody got paid to chase. You don't feel the gap on day one. You feel it when the floor cups or the wall smells six months later, and by then the crew is long gone.
We're not on a carrier's preferred list, by design. Our calls don't come from an insurance company, so we don't owe one. That means we answer to you. We write the scope your loss actually needs, document every bit of it, and stand on it with your adjuster. Advocating for the homeowner isn't a slogan for us. Staying independent is how we can actually do it.
Why waiting can actually cost you
Three reasons speed beats shopping when it comes to emergency water work.
- Mold starts fast. It can begin growing on wet materials in 24 to 48 hours. EPA guidance is to dry water-damaged areas within that same 24 to 48 hour window. Bids take days. Mold doesn't wait.
- Your policy expects you to act. Most homeowners policies include a "duty to mitigate," meaning you're expected to take reasonable steps to prevent further damage promptly. Sitting on a wet house while you gather quotes can work against your claim. Check your specific policy and ask your adjuster.
- The price per item is fixed. As we covered, mitigation is priced in Xactimate, used by roughly 80 percent of carriers. Collecting quotes doesn't lower the unit rate. It only surfaces who will do the least. The lever isn't the price. It's the scope.
How to actually use AI when water hits
AI can help a lot here, if you ask it the right way. Generic questions get generic answers, like "get three estimates." Specific questions get useful ones. Tell it your situation, your location, and that it's an emergency. Try these, word for word, and swap in your details:
What actually matters when you pick a company
Not three slow quotes. Speed, trust, and documentation. Here's what to look for, and what we bring.
Not filing a claim? This matters even more.
Plenty of water losses never touch insurance. Maybe it's small and falls under your deductible. Maybe you'd rather not file and nudge your premium up. Both are smart, common calls.
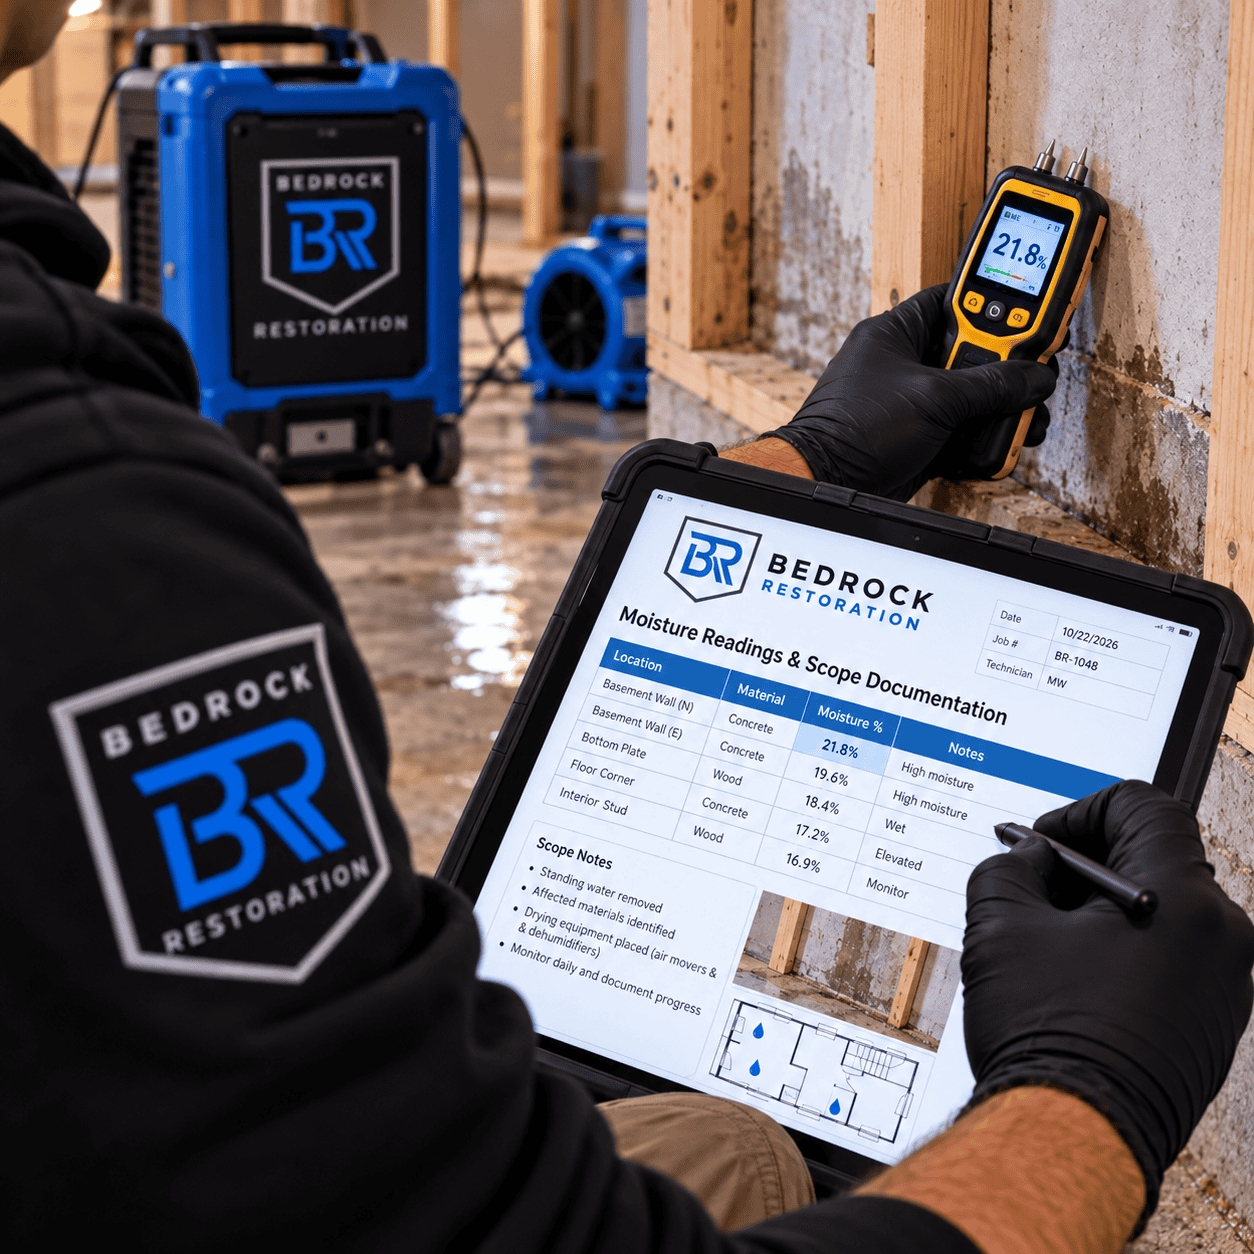
Here's the good news. When you're paying out of pocket, that same fixed-price system works for you, as long as the company is honest. Because every bit of the work is measured and logged in Xactimate, a transparent company can charge you for exactly what they did, and nothing more. Every fan. Every day of drying. Every foot of drywall. On the record.
So whether you file or not, insist on three things:
- Real documentation. Photos, moisture readings, and daily equipment logs, not a handshake.
- An itemized estimate. A line-by-line Xactimate scope, not a single lump-sum number.
- Charges that match the work. You pay for what was actually done, measured, not guessed.
We document every job the same way, claim or no claim. If you're paying yourself, you get the same line-item transparency, and you only pay for the work we actually do. That's the whole idea behind doing it right.
The bottom line
You don't need three estimates to start emergency water mitigation. That advice is built for remodels. For an active water loss, speed protects your home and your claim, the pricing is already standardized, and most policies expect you to act fast.
And when an insurer asks you for three, remember what it's for: finding the cheapest number, not the best outcome for your home. In Minnesota the choice is yours by right. You are not required to take the lowest bid, and you are not required to use their contractor. You choose.
Where bids do belong is the reconstruction phase, after the house is dry. That's a planned job with time to compare. Two different phases, two different playbooks.
If you want a sense of the numbers first, see our plain-English water damage cost guide.
Quick answers
Water in your home right now?
Skip the three quotes. Call a real local team that answers the phone, gets on-site fast, documents everything, and manages your claim. We'll tell you what we found and what happens next.
612-834-1501This guide is general information for Twin Cities homeowners, not legal or insurance advice and not a quote. Insurance policies vary, so always check your specific policy and talk to your adjuster. Mold timing reflects general industry and EPA guidance; the 24 to 48 hour window can shift with conditions. "Duty to mitigate" language and estimate requirements differ by policy and carrier.