


A burst pipe or overflowing appliance may qualify. Flooding from outside, sewer backups without additional coverage, and gradual leaks are commonly excluded. Where the water came from, how it happened, and your policy terms determine coverage.
It's 11 p.m. You walk downstairs and find water spreading across your finished basement. Maybe a pipe burst behind the wall. Maybe your sump pump stopped during a storm.
You ask Google or ChatGPT, “Does homeowners insurance cover water damage?” The usual answer is “it depends.” That's true, but not very helpful. Two basements with the same amount of water can have completely different insurance outcomes. Here's how coverage generally works in Minnesota and what matters while the house is still wet.
What types of water damage does homeowners insurance usually cover?
Sudden and accidental water damage is generally more likely to be covered than flooding, gradual leaks, or maintenance-related damage.
The Minnesota Department of Commerce explains that standard homeowners policies commonly treat broken pipes differently from floodwater and water backup.
| Water source | Typical treatment |
|---|---|
| Burst pipe inside the house | Often covered |
| Washing machine hose suddenly breaks | Often covered |
| Water heater unexpectedly leaks or ruptures | Resulting damage may be covered |
| Sudden accidental plumbing overflow | Often covered |
| Slow leak behind a wall for months | Often excluded |
| Sump pump failure | Usually needs added coverage |
| Sewer or drain backup | Usually needs added coverage |
| River or surface water entering the home | Generally excluded from standard policies |
| Groundwater through basement walls | Generally excluded |
These are common coverage patterns, not guarantees. Did something inside the house suddenly fail, or did water enter from outside or build up over time? That distinction often changes the conversation.
Does homeowners insurance cover water damage from a burst pipe?
Yes. Sudden damage from a burst pipe is commonly covered.
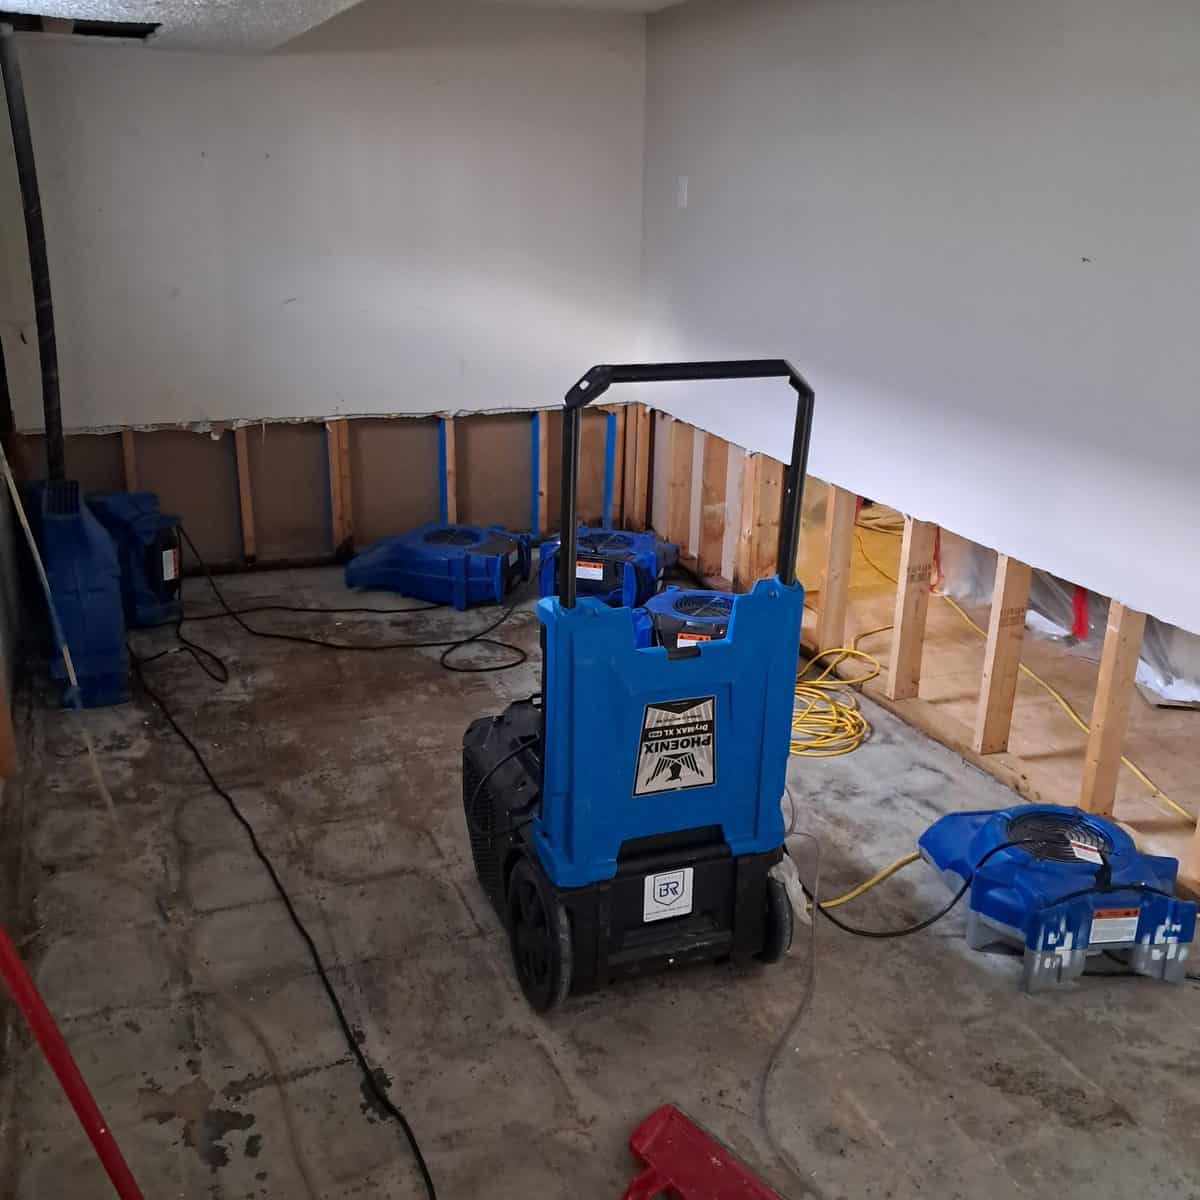
Imagine a pipe freezing during a Minnesota winter and splitting behind the kitchen wall. Water spreads across the floor and reaches the basement. A typical policy may cover the resulting drying, damaged materials, and necessary reconstruction.
The Minnesota Department of Commerce provides homeowners insurance guidance. At Bedrock Restoration, we also own Bedrock Plumbing & Drain Cleaning. Our plumbing team can address the broken pipe while the restoration team handles water removal, drying, and reconstruction.
Does homeowners insurance cover basement flooding?
Sometimes. Basement coverage depends on the source of the water.
The resulting water damage may be covered because the source was a sudden plumbing failure.
These losses often need separate coverage or are excluded from standard homeowners policies.
A failed sump pump during a storm and a burst supply pipe can leave identical wet carpets. Insurance may treat them differently. See the Minnesota Department of Commerce for state consumer guidance.
Does homeowners insurance cover sump pump or sewer backup damage?
Usually only when the homeowner purchased appropriate additional coverage.
Many Twin Cities homes rely on sump pumps. If one fails during heavy rain, the resulting basement damage may fall outside a standard policy. Sewer backups are commonly handled through a separate water backup endorsement too.
An insurance agent can verify the exact endorsement, its limits, and which water sources it covers. The Minnesota Department of Commerce offers homeowners insurance consumer information.
Does homeowners insurance cover slow leaks and mold damage?
Gradual water damage is often excluded, especially when it develops from ongoing leakage or neglected maintenance.
A slow leak beneath a bathroom sink that damages cabinets over months is different from a pipe that breaks and floods the room suddenly. Mold coverage may depend on the original water source, policy limits, and exclusions.
Read the EPA mold cleanup guidance. A wet wall needs attention regardless of who ultimately pays.
What happens immediately after water damage if coverage is uncertain?
The source needs to be stopped safely, the loss documented, and affected materials dried promptly.
The Minnesota Department of Commerce recommends documenting damage and taking reasonable steps to avoid additional loss while coordinating with the insurer before permanent repairs.
- Safety first. Stay clear of standing water near electrical equipment and contaminated sewer water.
- Stop the source when safe. An active leak can continue damaging the home.
- Document the damage. Photos and video show the condition of rooms and belongings.
- Begin appropriate water removal and drying. Hidden moisture may require professional equipment.
- Coordinate insurance instructions. An agent or adjuster can explain reporting and inspection requirements.
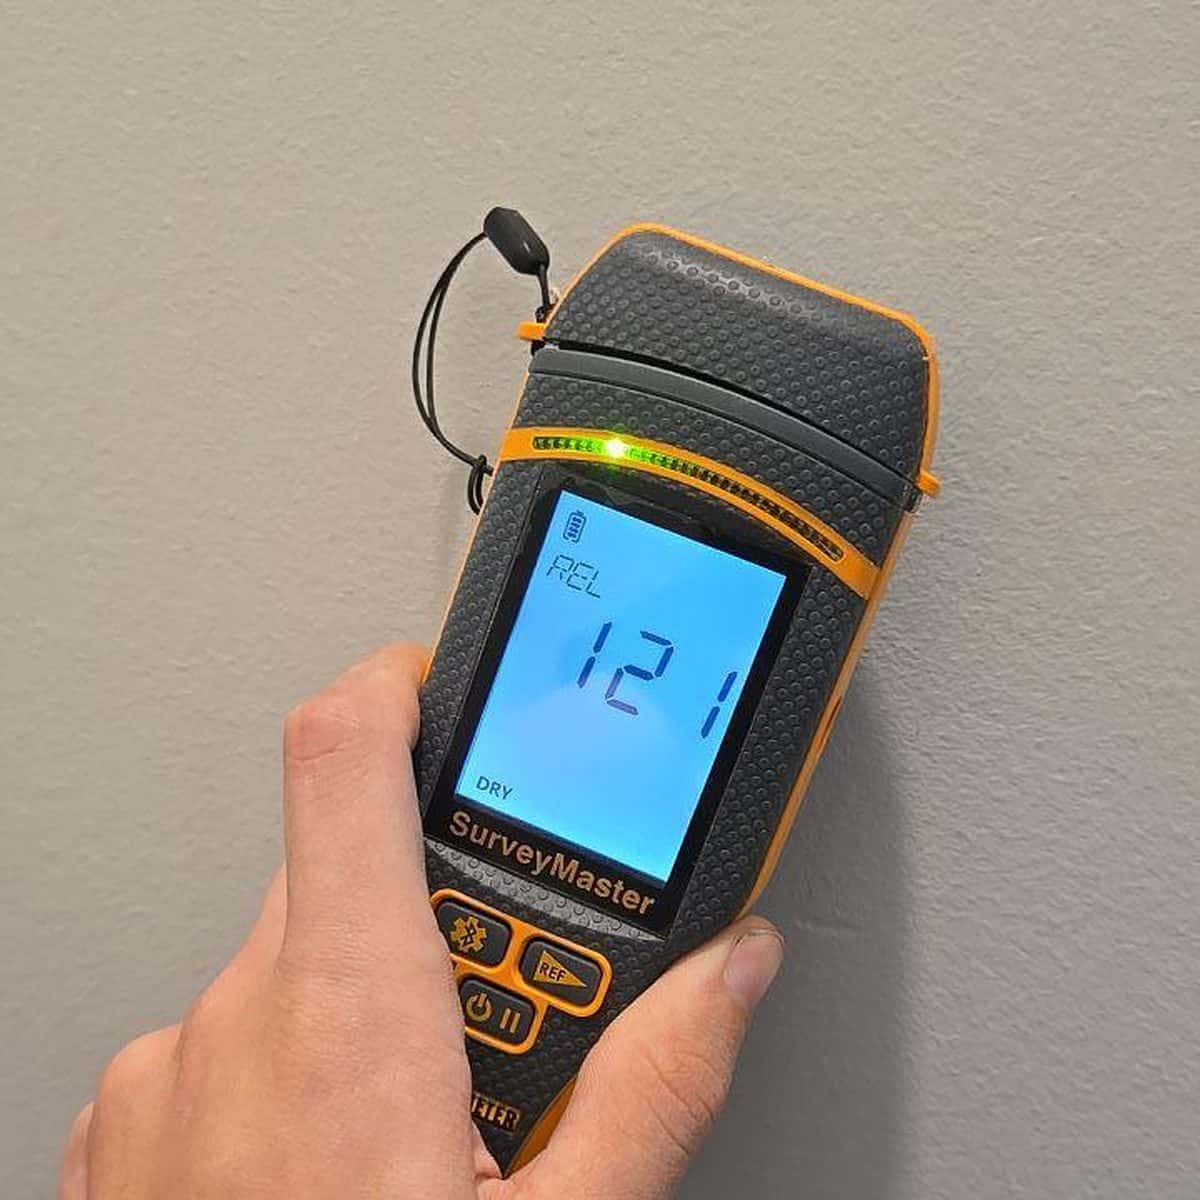
Emergency drying and permanent reconstruction are different steps. Bedrock documents moisture readings, affected materials, and a written repair scope. Learn more about our water damage restoration services.
Will insurance pay the entire restoration bill?
Not necessarily. A covered water loss can still involve a deductible, limits, or uncovered expenses.
Example assumes the full repair amount is covered, one deductible applies, and no other adjustment changes the payment.
Bedrock uses Xactimate to document repair quantities and pricing. Standardized estimating tools make an itemized scope easier to review, although the final numbers can differ based on the work included and job conditions.
A lower estimate may reflect fewer repairs. It can also reflect pricing or quantity differences. What matters is whether the complete necessary repair scope is documented.
See our water damage restoration cost guide.
Do I have to use the contractor recommended by my insurer?
No. Minnesota homeowners generally can choose their own restoration contractor.
Insurance companies sometimes recommend preferred vendors. A recommended contractor can be capable and qualified, but the homeowner can evaluate other options.
Bedrock Restoration operates independently of insurer preferred vendor programs. We document the damage, prepare a repair scope, and communicate about our restoration work with the adjuster.
The homeowner can compare responsiveness, experience, and repair scope. For questions about insurer conduct, contact the Minnesota Department of Commerce.
How can Bedrock Restoration help when insurance is involved?
Bedrock can manage the physical restoration and document the work for the insurance process.
Our job is to explain the damage and restore the home properly.
The bottom line
Homeowners insurance often covers sudden accidental water damage. Slow leaks, groundwater flooding, and sewer or sump pump backups are commonly excluded unless specific coverage applies.
The most useful framework is the water source, the way the damage happened, and the exact policy language. Your agent or adjuster determines coverage. Bedrock Restoration can assess and document the repair needs.
Whatever insurance decides, water still needs to be stopped and affected materials dried promptly.
Quick answers
Does homeowners insurance cover water damage from a burst pipe?
Yes, homeowners insurance commonly covers sudden and accidental water damage caused by a burst pipe. Coverage may include drying, removal of damaged materials, and necessary reconstruction. The pipe repair itself may be treated separately.
Does homeowners insurance cover water damage from a leaking roof?
It may, depending on what caused the roof to leak. Sudden damage from a covered windstorm may qualify, while damage from an old or poorly maintained roof may be excluded. Your adjuster can determine coverage.
Does homeowners insurance cover water damage in a basement?
Basement water damage may be covered when it comes from a sudden indoor plumbing failure. Groundwater, foundation seepage, and sump pump failures are commonly excluded from standard policies. Additional coverage may change the outcome.
Does homeowners insurance cover water damage from a washing machine?
Homeowners insurance often covers sudden damage caused by a broken washing machine hose or accidental overflow. Damage from ongoing leaks or neglected maintenance may be excluded. Coverage for replacing the appliance can differ from coverage for damaged floors.
Does homeowners insurance cover water damage from a water heater?
Sudden and accidental water damage from a failed water heater may be covered. The resulting damage to the home can be treated differently from replacing the water heater itself. The cause and policy terms determine coverage.
Does homeowners insurance cover mold after water damage?
Mold may be covered when it directly results from a covered water loss, subject to limits and exclusions. Long-term moisture problems are commonly excluded. The EPA recommends drying wet materials within 24 to 48 hours.
Does homeowners insurance cover water damage from a sump pump failure?
Standard homeowners insurance typically does not cover sump pump failure damage. An additional water backup endorsement may provide protection, subject to limits and exclusions. Your agent can verify the actual coverage.
Does homeowners insurance cover sewer backup damage?
Sewer backup is generally excluded from standard homeowners policies unless special backup coverage was purchased. Coverage limits and qualifying circumstances vary. Your agent can review the endorsement with you.
Does homeowners insurance pay for restoration and reconstruction?
Insurance may cover necessary drying, damaged material removal, and reconstruction when the underlying loss is covered. The payment depends on the deductible, limits, and approved scope. A restoration company documents the work while the insurer determines covered costs.
Can I choose my own water damage restoration company if insurance pays?
Yes. Minnesota homeowners generally can select their own restoration contractor. The insurance company may recommend a preferred vendor, but the homeowner can select an independent company such as Bedrock Restoration. Coverage and payment remain subject to the policy.
Water damage in your home? We're available 24/7.
A wet basement or leaking pipe needs attention while insurance coverage is reviewed. We document the damage and handle restoration, with plumbing support when needed.
612-834-1501General information disclaimer: This article provides general educational information, not insurance, financial, or legal advice. Bedrock Restoration is a water damage restoration company, not an insurance agency or law firm. Policies, deductibles, endorsements, exclusions, and coverage decisions vary. Consult your insurance agent or adjuster about your specific policy and an appropriately licensed professional for legal or other specialized advice. Examples do not guarantee payment.